Are you dreaming of owning your first home in the Ocean State but feeling sidelined by upfront costs? There is great news for Rhode Islanders today.As of March 10, 2026, the Realtor Foundation:

Dated: November 21 2023
Views: 2717
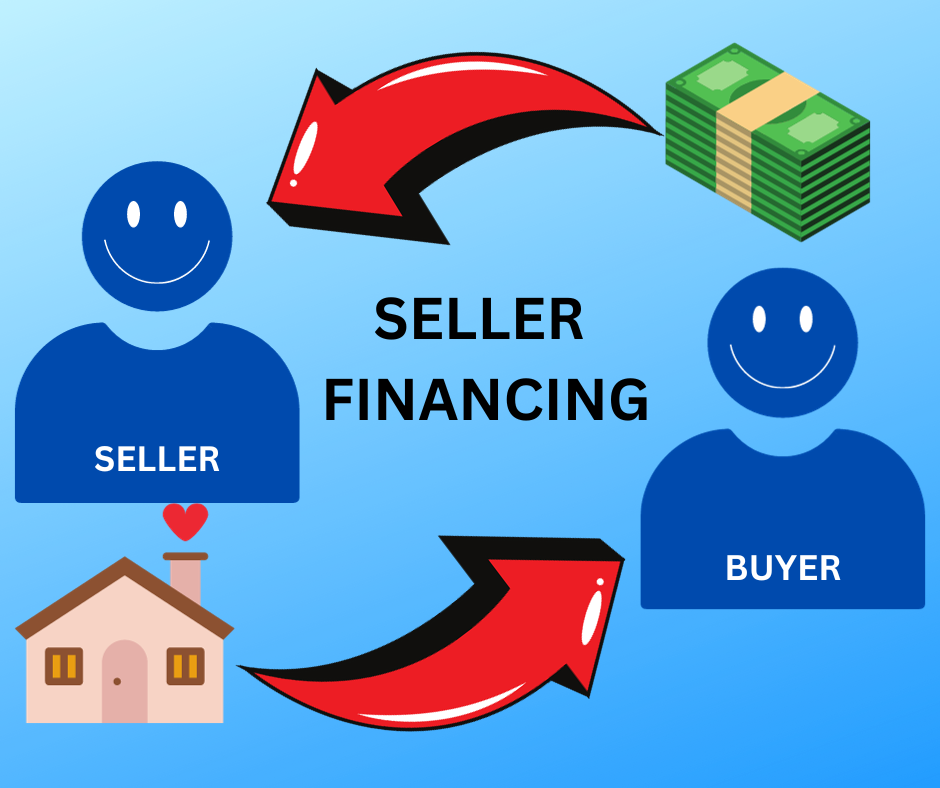
Owner financing, also known as seller financing, is a real estate transaction where the seller acts as the lender, providing a loan to the buyer. Instead of the buyer securing a loan from a bank, the seller offers a loan to the buyer for the purchase of the property. The buyer agrees to pay back the loan over time, typically with interest, according to agreed terms. This method can be beneficial in situations where traditional bank financing is not available or desirable.
Pros of Owner Financing for Buyers:
1. Simplified Transaction: The buying process can be faster and less bureaucratic than traditional bank financing.
2. Flexible Terms: Terms such as down payment, interest rate, and repayment schedule can be negotiated directly with the seller.
3. No Banking Qualifications: Buyers who might not qualify for traditional loans due to credit issues or self-employment might have better chances with owner financing.
4. Potential Cost Savings: There may be savings on closing costs and bank fees.
Cons of Owner Financing for Buyers:
1. Higher Interest Rates: Sellers may charge higher interest rates than banks.
2. Large Down Payment: Sellers often require a sizable down payment to protect their investment.
3. Shorter Loan Period: Seller-financed loans may need to be repaid sooner, often with a balloon payment.
4. Default Risk: If the buyer defaults, they can lose the property and all the money paid towards it.
5. Property Condition: Sellers might be less motivated to address property issues or make repairs.
Owner Financing vs. Traditional Financing:
Interest Rates: Traditional loans might offer lower interest rates.
Loan Terms: Banks usually offer longer loan terms, which can make monthly payments more affordable.
Purchase Protection: Banks require appraisals, inspections, and title insurance, which can protect the buyer.
Equity Building: Traditional loans typically facilitate building equity over time without large balloon payments.
Risks for Buyers in Owner Financing:
1. Balloon Payments: A large lump-sum payment may be due at the end of the loan term, which the buyer must be able to pay or refinance.
2. Seller’s Financial Stability: If the seller has a mortgage on the property and fails to make their payments, the bank can foreclose on the property.
3. Legal Complications: The legalities of owner financing can be complex, and buyers should have a clear, legally binding contract.
4. Market Changes: If property values decline, buyers could end up owing more than the home is worth, especially with a high-interest rate.
5. Lack of Prepayment Benefits: Unlike some traditional loans, there may be no benefit to prepaying the loan to reduce interest.
When considering owner financing, it’s crucial for a buyer to conduct thorough due diligence, understand all the terms, and ideally consult with a real estate attorney. While it can offer a viable alternative to traditional lending, owner financing carries its unique set of risks and benefits that need careful consideration.
Owner financing, when the seller of a property provides financing to the buyer, can be an attractive option for sellers in certain circumstances. Here’s a breakdown of the concept from a seller's perspective, including the advantages and disadvantages, a comparison with traditional buyer financing, and potential risks.
Pros of Owner Financing for Sellers:
1. Attract More Buyers: By offering owner financing, sellers can attract buyers who may not qualify for traditional loans.
2. Faster Sale: Sellers might be able to sell the property faster as the buyer doesn't have to undergo the lengthy bank mortgage process.
3. Higher Interest Rates: Sellers can often charge a higher interest rate than banks, which can lead to more income over time.
4. Tax Advantages: Spreading out the receipt of the home’s purchase price over several years can potentially offer tax benefits.
5. Increased Selling Price: Buyers may be willing to pay more for the convenience of owner financing.
Cons of Owner Financing for Sellers:
1. Default Risk: If the buyer defaults on the loan, the seller must foreclose and take back the property, which can be costly and time-consuming.
2. Liquidity: The seller will not receive a lump sum upfront but rather payments over time, which may not be ideal if immediate cash is needed.
3. Market Risks: If the market declines, the property could be returned to the seller worth less than when they sold it.
4. Maintenance Obligations: Some owner financing agreements may require the seller to handle major repairs if the buyer defaults early on.
Owner Financing vs. Traditional Buyer Financing:
Control: With owner financing, the seller has more control over the terms of the sale.
Market Conditions: In a slow market, offering owner financing can make a property stand out.
Payment Security: Traditional financing ensures that the seller receives the full payment upfront upon closing.
Risks for Sellers in Owner Financing:
1. Buyer’s Financial Stability: There’s a risk that the buyer may stop making payments due to financial difficulties.
2. Legal Complexity: Owner financing agreements can be complex and must be structured properly to protect the seller’s interests.
3. Prepayment: Buyers may pay off the loan early, which could reduce the anticipated interest income for the seller.
4. Estate Planning Complications: If the seller dies before the loan is paid off, the seller's heirs will inherit the payment stream, which may not align with estate planning goals.
For sellers considering this option, it is important to vet the buyer's creditworthiness thoroughly, secure a substantial down payment, and have a well-drafted agreement that includes a clear foreclosure process in case of default. It's often wise to work with a real estate attorney to navigate the complexities and ensure that the deal is structured favorably. While owner financing can be beneficial, it's not without its challenges and should be approached with a full understanding of the financial implications.
Introducing Keith, a dedicated and highly motivated real estate agent who has been helping clients achieve their real estate goals since 2019. With a laser focus on delivering exceptional results, Kei....
Are you dreaming of owning your first home in the Ocean State but feeling sidelined by upfront costs? There is great news for Rhode Islanders today.As of March 10, 2026, the Realtor Foundation:
Not all senior living communities are the same—and that's a good thing. Whether you're planning ahead or helping a loved one, here's a breakdown of the most common types of senior housing and
Once you've been pre-approved for a mortgage and are in the process of looking for a home, there are certain things you should avoid doing to ensure that your mortgage approval remains valid and
Selling your home can be as challenging as it is exciting. To navigate this complex process and achieve a swift, profitable sale, leveraging expert real estate tips is crucial. In this blog, we
 IDX information is provided exclusively for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information is deemed reliable but is not guaranteed. © 2026 State-Wide Multiple Listing Service. All rights reserved.
